16 Oct 2026 Notes 3 min read
No Loyalty to a Market (Must Be Nice)
No loyalty to a market. No loyalty to a narrative. Only loyalty to risk-adjusted returns.
 Thoriq Faisal Yahya
On October 2, a fund manager named Ricky Ho published an elegant goodbye letter to Indonesia. He had warned about absurd valuations in conglomerate stocks last December, told everyone to avoid Indonesian equities in February, bought selectively in July, made his money, and then sold everything. His closing line:
No loyalty to a market. No loyalty to a narrative. Only loyalty to risk-adjusted returns.
Two weeks later, on October 16, the Indonesian market read the letter and took it personally.
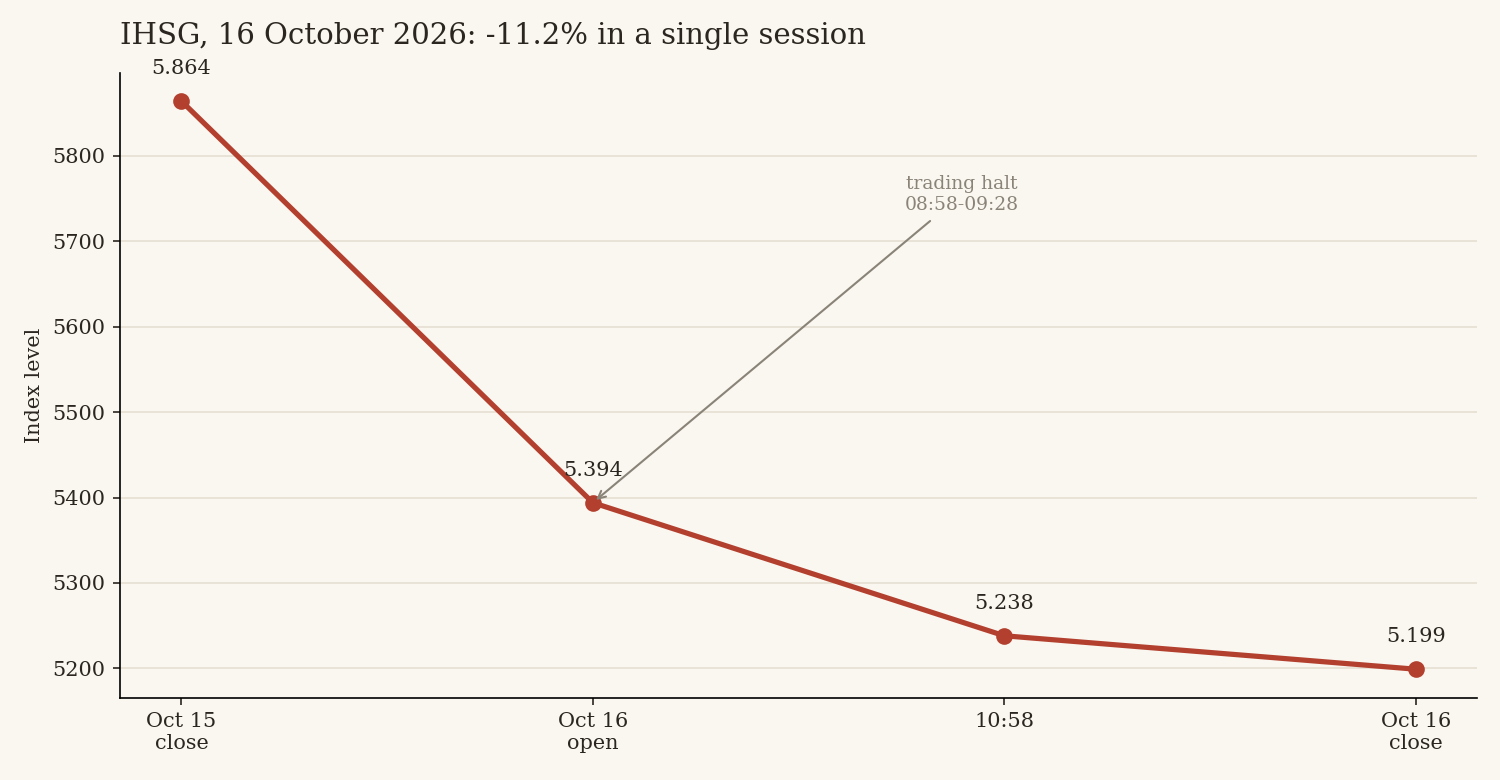
The exchange halted trading at the open, then kept falling until the index closed at 5,185.11, down 11.57 percent on the day. Measured against last Friday’s verified close of 6,093.76, that is 14.91 percent destroyed in a single week, on turnover of Rp31.74 trillion. The breadth tells the story better than the index: 812 shares fell, 11 rose, 140 stood still. That is not a correction. That is a fire drill where someone locked the exits.
The trigger was MSCI opening a consultation, note: a consultation, not a downgrade yet, on moving Indonesia from Emerging Market to Standalone status. Its stated concerns: ownership transparency, suspected coordinated trading, and insufficient evidence that reforms are actually working. The decision lands by 30 June 2027. Read “Standalone” slowly. It is the index world’s polite way of saying: we are not sure your market is a real market.
The rupiah joined in. Bank Indonesia’s JISDOR printed Rp18,052 per dollar, weaker than Rp17,948 the day before. Foreigners kept selling. I will not quote you a full-day foreign-flow number, because the verified one does not exist yet and the midday figure is not the close, and I have decided to stop laundering guesses into facts.
Here is the part that stings. Ho’s letter was not wrong. US yields at multi-decade highs, a rampaging dollar, oil above $100, banks with questionable asset quality, a middle class whose purchasing power exists mostly in GDP presentations. He read the macro, took his profits, and left. That is his job. “Only loyalty to risk-adjusted returns.” Elegant. Honest, even.
But notice the asymmetry. A family office can be loyal only to returns because it can leave. My loyalty to this market was never loyalty. It was illiquidity, hope, and the national pastime of averaging down. Retail investors do not get goodbye letters. We get the halt, the red portfolio, and a push notification.
So let us be precise about what happened, because precision is a form of fighting. This was not “global headwinds.” Other emerging markets faced the same dollar and the same oil. This was a market whose own regulator could not convince the world its prices are real. When the index provider questions your transparency and your enforcement, and your response is an 11.57 percent crash in a day, you have not rebutted the claim. You have cosigned it.
Cheap markets stay cheap for a long time when the catalyst for re-rating is political. And politics in Indonesia right now is giving us nothing to work with.